When Official Records Stop Capturing the Solar Buildout
The grid impacts of Pakistan’s distributed solar generation have grown faster than the records meant to track them. Utility interconnection data covers what has been registered; it does not cover what is installed and running behind the meter. Reconstructing the difference means drawing on customs records, Chinese panel export data and satellite imagery, cross-checked against one another. What emerges is a market in which the visible, registered share is only part of the story, leaving a measurement gap that no register closes.
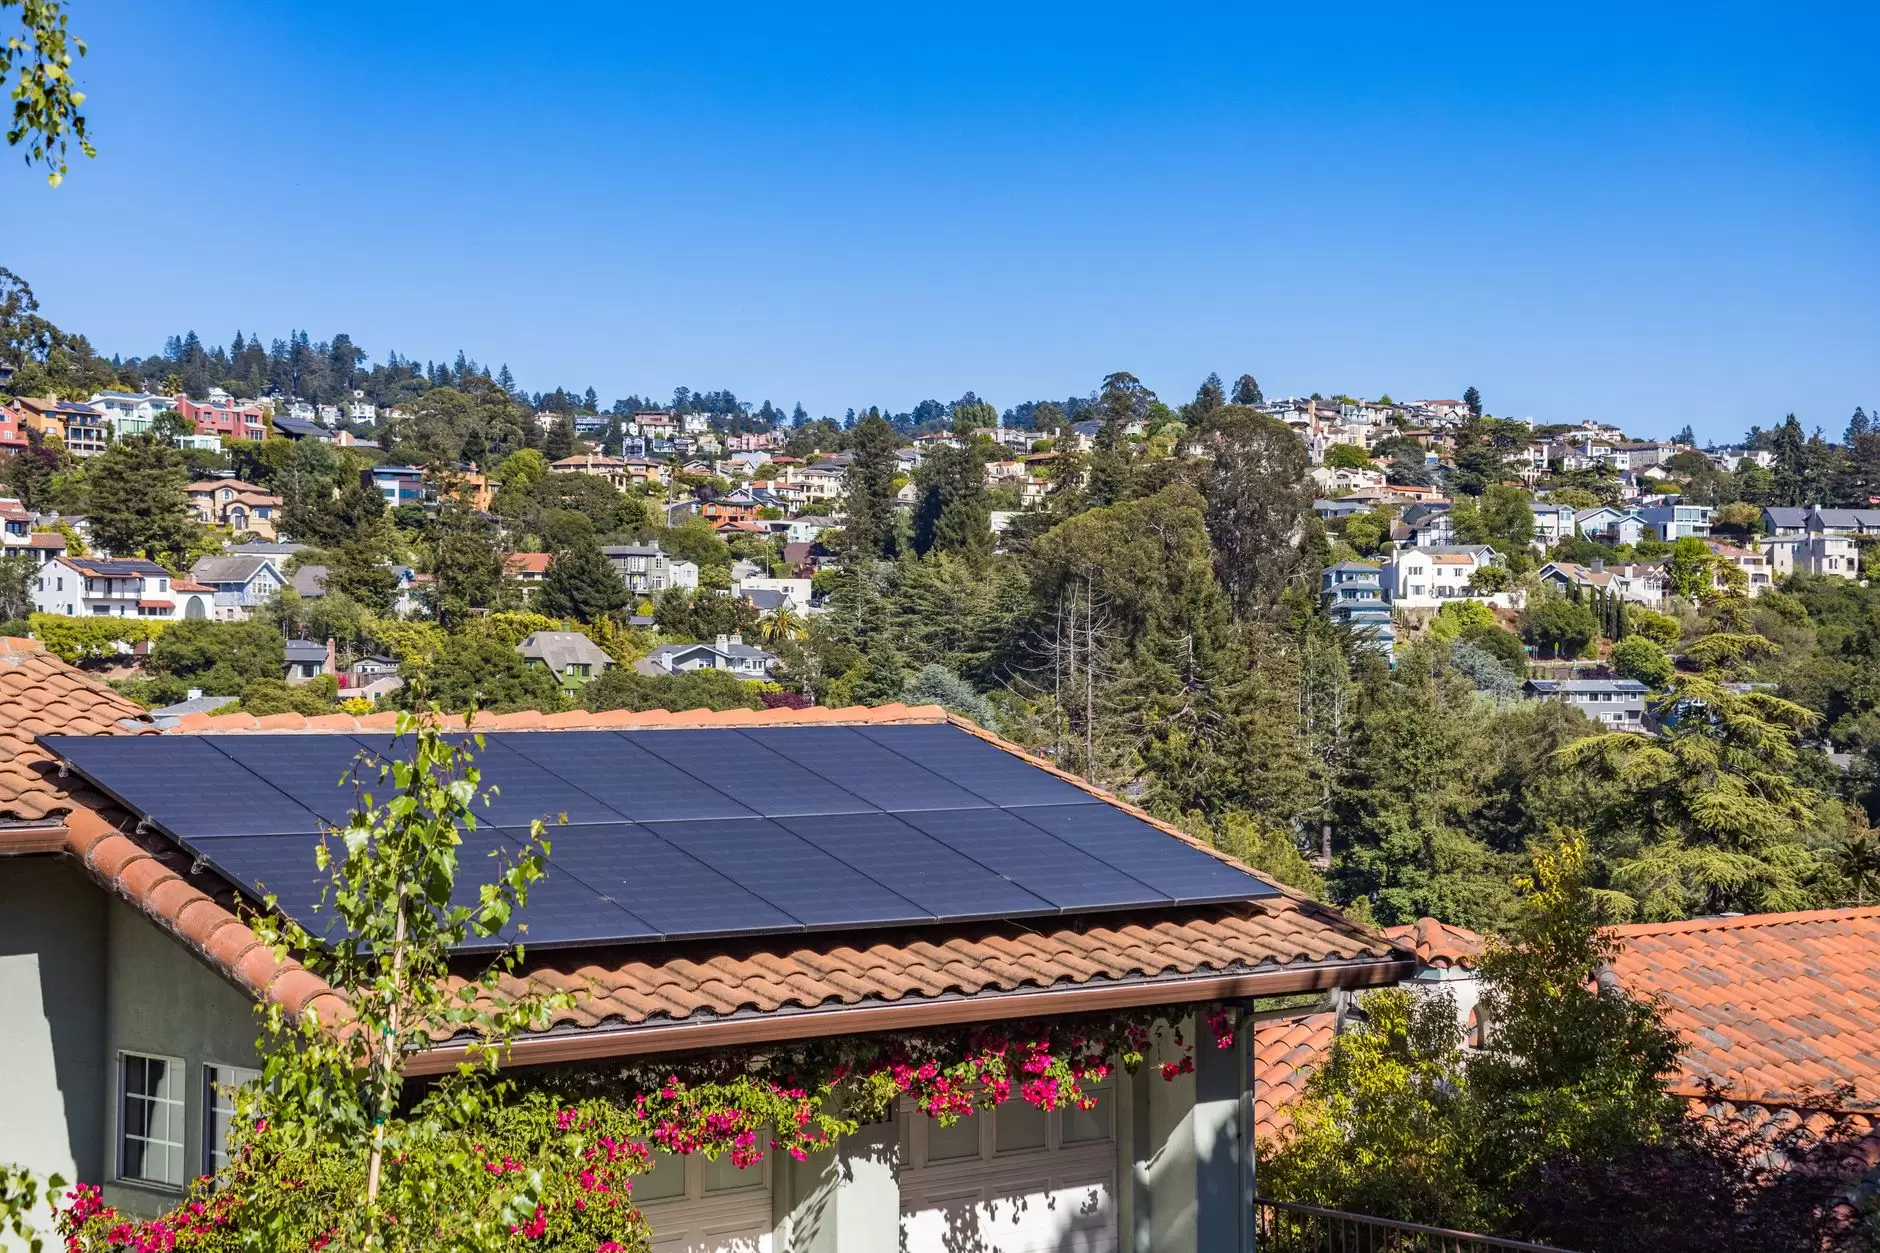
That measurement gap matters because grid planning depends on knowing how much generation sits behind the meter. Absent that information, system operators cannot reliably anticipate midday load, forecast demand or plan network reinforcement. Pakistan is therefore confronting a data problem as much as an energy transition problem.
The boom follows a pattern described as leapfrogging, where countries adopt new energy technology without first passing through the same stages of fossil-fuel development as wealthier countries did. It occurs when the technology is already proven in mature markets, offers comparable functionality and provides a way around expensive or dysfunctional infrastructure.
In Pakistan, that third condition has been especially visible. Grid supply remains unreliable in parts of the country, and tariff increases have made self-generation more attractive. Rooftop solar offers a way around both problems for the households and businesses that can afford the upfront investment.
Affordability shapes who participates. A study by researchers from Pakistan and the United Kingdom found that registered net metering is concentrated among higher-income customers in the best-served utility areas. Unregistered off-grid and behind-the-meter systems dominate where the grid is least reliable. This splits the boom into two channels that follow different logics.
Two Solar Economies, One Grid
The registered channel operates inside the formal system. It draws on net metering connections, where customers in well-served areas export surplus generation into the grid. These adopters tend to be concentrated in areas with better utility performance, which reduces the reliability motive but leaves the economics of bill reduction at work.
The unregistered channel is different. Off-grid and behind-the-meter systems dominate where electricity supply is least dependable. These systems often have no export connection at all, or are not recorded by the utility. They are a response to load-shedding and high backup costs more than to export tariffs.
This split tracks income and service quality rather than a single solar economics. Better-served areas host visible, metered adoption, while the areas with the weakest service host hidden adoption. For planners, that means official interconnection data understates the system where reliability is already under stress.
The tension between these two channels echoes questions raised elsewhere in South Asia. Sri Lanka’s energy crisis asked whether distributed solar can provide energy security when the wider system is under stress. Pakistan’s two-track boom suggests the answer depends on which customers adopt solar and whether that adoption is visible to the system.
The Utility Revenue Loop
The utility revenue problem is often framed as a death spiral. When households and businesses that can afford solar cut their grid consumption, utilities lose revenue. Fixed costs are then spread across a smaller number of units sold, pushing tariffs higher, which makes solar even more attractive.
Pakistan’s version of that loop operates unevenly across the two channels. The registered net metering channel has a direct interaction with the tariff structure, because net metered customers alter billed consumption and export credits. The unregistered channel does not appear in billing at all, which removes revenue without any corresponding record.
What makes the situation acute is that the registered channel draws disproportionately from higher-income customers in well-served areas. Those customers often account for a large share of stable revenue, not because they necessarily use the most electricity, but because they pay consistently and in full. Their shift toward self-consumption concentrates fixed-cost recovery on a narrower base.
NEPRA responded to that revenue pressure with a regulatory shift. In February, NEPRA replaced net metering with net billing for new connections. The change governs only the visible boom, because unregistered systems by definition sit outside the formal connection process and therefore never appear in the tariff decision.
Researchers said the net billing change is likely to slow registered adoption, make battery storage and self-consumption more attractive, and push marginal adopters into the unregistered segment. The formal policy may therefore not reduce the hidden boom so much as redirect it into channels that are harder to measure.
What Net Billing Can and Cannot Do
Net billing changes the compensation for exported generation, reducing the incentive to push surplus power onto the grid. That rewards customers who size systems to meet their own load rather than to export. The objective is to slow the revenue loss associated with compensating exports at rates that make the grid less affordable for everyone else.
But the policy operates only on the registered channel. Off-grid and behind-the-meter systems that never had export arrangements were never part of the net metering ledger, so they are untouched by changes to export tariffs. A customer installing a small off-grid system to avoid load-shedding is not affected by the new billing rules. The reform is therefore narrower than the problem it addresses.
In fact, the researchers suggested the reform may increase the unregistered segment. If registered adoption becomes less attractive, marginal adopters may skip the formal process altogether and install systems that never appear in utility records. That would deepen the measurement problem even as the formal market slows, leaving planners with an even less complete picture of distributed capacity.
Battery storage becomes more attractive under net billing because self-consumption gains value when exports are less rewarded. Customers may add batteries to shift solar output into evening hours, reducing purchases from the grid without relying on export credits. The next wave of investment may therefore shift toward storage rather than additional panels.
Measuring the Invisible
The core planning challenge is measurement, not technology. Without accurate data on behind-the-meter capacity by region, utilities and regulators cannot assess how much midday load has been displaced, how much backup demand remains, or where system constraints are developing. The result is a planning process that runs partly on inference.
The study authors called for a standing program to measure behind-the-meter capacity by region using customs data, installer registrations, surveys and feeder-level daytime load. This combines several imperfect signals into a more reliable picture of what is actually installed, since no single source captures the unregistered segment on its own.
Feeder-level daytime load is useful because it reveals demand that disappears when solar output rises. Comparing actual midday load against what would be expected without distributed generation shows the scale of behind-the-meter supply affecting the network. The signal is indirect but observable, and it grows stronger as more capacity sits unregistered.
The measurement approach also matters for equity. If higher-income customers are leaving the grid through registered connections while lower-income customers remain dependent on a strained utility, tariff design becomes a distributional question as well as a technical one. Data gaps then shape who bears the cost of maintaining the network.
Where Pakistan Sits in the Regional Pattern
Pakistan’s experience is part of a wider Asian pattern in which distributed solar is growing faster than the planning systems designed to accommodate it. The Asia-Pacific energy transition shows similar tensions between policy ambition and grid capacity, though each market arrives at them from a different starting point.
India’s electricity sector offers a comparison. Growth there has outpaced the grid in ways that create similar strain between centralized planning and rapid behind-the-meter adoption, though India’s scale and grid characteristics differ. Malaysia’s power sector shows the same tension from a different starting point, where gas and independent power producer contracts shape how new distributed supply affects incumbent utilities.
Vietnam’s transition shows another dimension, where grid congestion emerged from rapid utility-scale renewable build-out. Pakistan’s challenge is more distributed, but both illustrate that generating capacity can move faster than the physical and institutional capacity to integrate it. The integration bottleneck takes different forms across the region.
What Planners Should Watch
The immediate policy question is how utilities and regulators respond to the measurement gap. A standing data program along the lines the study authors proposed would give the system a better basis for load forecasting and tariff design. Without it, decisions about network investment and cost allocation rely on incomplete information.
Net billing changes the composition of the registered market more than its total size. If storage becomes more attractive, the next wave of formal adopters may install hybrid systems rather than export-oriented arrays. That changes grid dynamics from one-way surplus exports to more self-balancing load patterns.
The unregistered segment is harder to shift through tariff policy. It responds to reliability and backup costs, which net billing does not touch. That segment grows or shrinks on the basis of grid performance and equipment prices, not on export compensation. Planners may therefore need to think of the hidden boom as a separate planning variable rather than a failed policy outcome.
References
- Jan Rosenow — “The Solar Boom Outrunning the Grid”: utility death spiral, leapfrogging criteria, and use of customs, export and satellite data to reconstruct deployment.
- pv magazine — “Prices drive Pakistan’s metered solar, outages drive hidden uptake”: NEPRA net billing change, study findings on two adoption channels, and proposal for a standing measurement program.