Green hydrogen production costs come down to three numbers: the price of renewable electricity, the capital cost of the electrolyser, and how many hours a year the plant actually runs. Those three variables explain most of the gap between announced projects and final investment decisions. In renewable-rich markets, they have narrowed the difference with fossil-based hydrogen enough to support subsidised projects. In other markets, the same variables keep green hydrogen well above the cost of fossil-based supply. The molecule itself is familiar to industry; what is new is the cost structure of producing it without a fossil feedstock.
Before hydrogen became a prominent decarbonization pathway, it was already a large industrial gas. Most existing production uses natural gas or coal, and the largest consumers are ammonia plants and refineries. Green hydrogen targets a molecule that industrial buyers already handle. The change concerns how it is produced, and that change carries a specific economic structure.
Why Green Hydrogen Re-entered the Conversation
Electrolysis has been used to produce hydrogen for decades, mostly at small scale. The current wave of interest comes from the interaction between two pressures. Power systems are adding large volumes of variable generation from solar PV and wind, which creates periods of very low electricity prices. An electrolyser can respond to those periods and convert surplus electricity into a storable gas. That capability positions green hydrogen as one option for long-duration storage and system balancing, even though the round-trip efficiency is poor.
The second pressure comes from industrial sectors that are difficult to electrify directly. Steelmaking, chemicals production and long-distance shipping require either intense heat or energy-dense fuels. Hydrogen can serve as a reducing agent in steel, as a feedstock for ammonia, and as a precursor for synthetic fuels. Policy interest in green hydrogen therefore combines two arguments: one about electricity system balancing and one about industrial decarbonization. System operators measure value in dispatch hours and grid services, while industrial buyers measure delivered cost per tonne of ammonia or steel. Green hydrogen has to straddle both conversations.
The Cost Structure That Separates Potential from Deployment
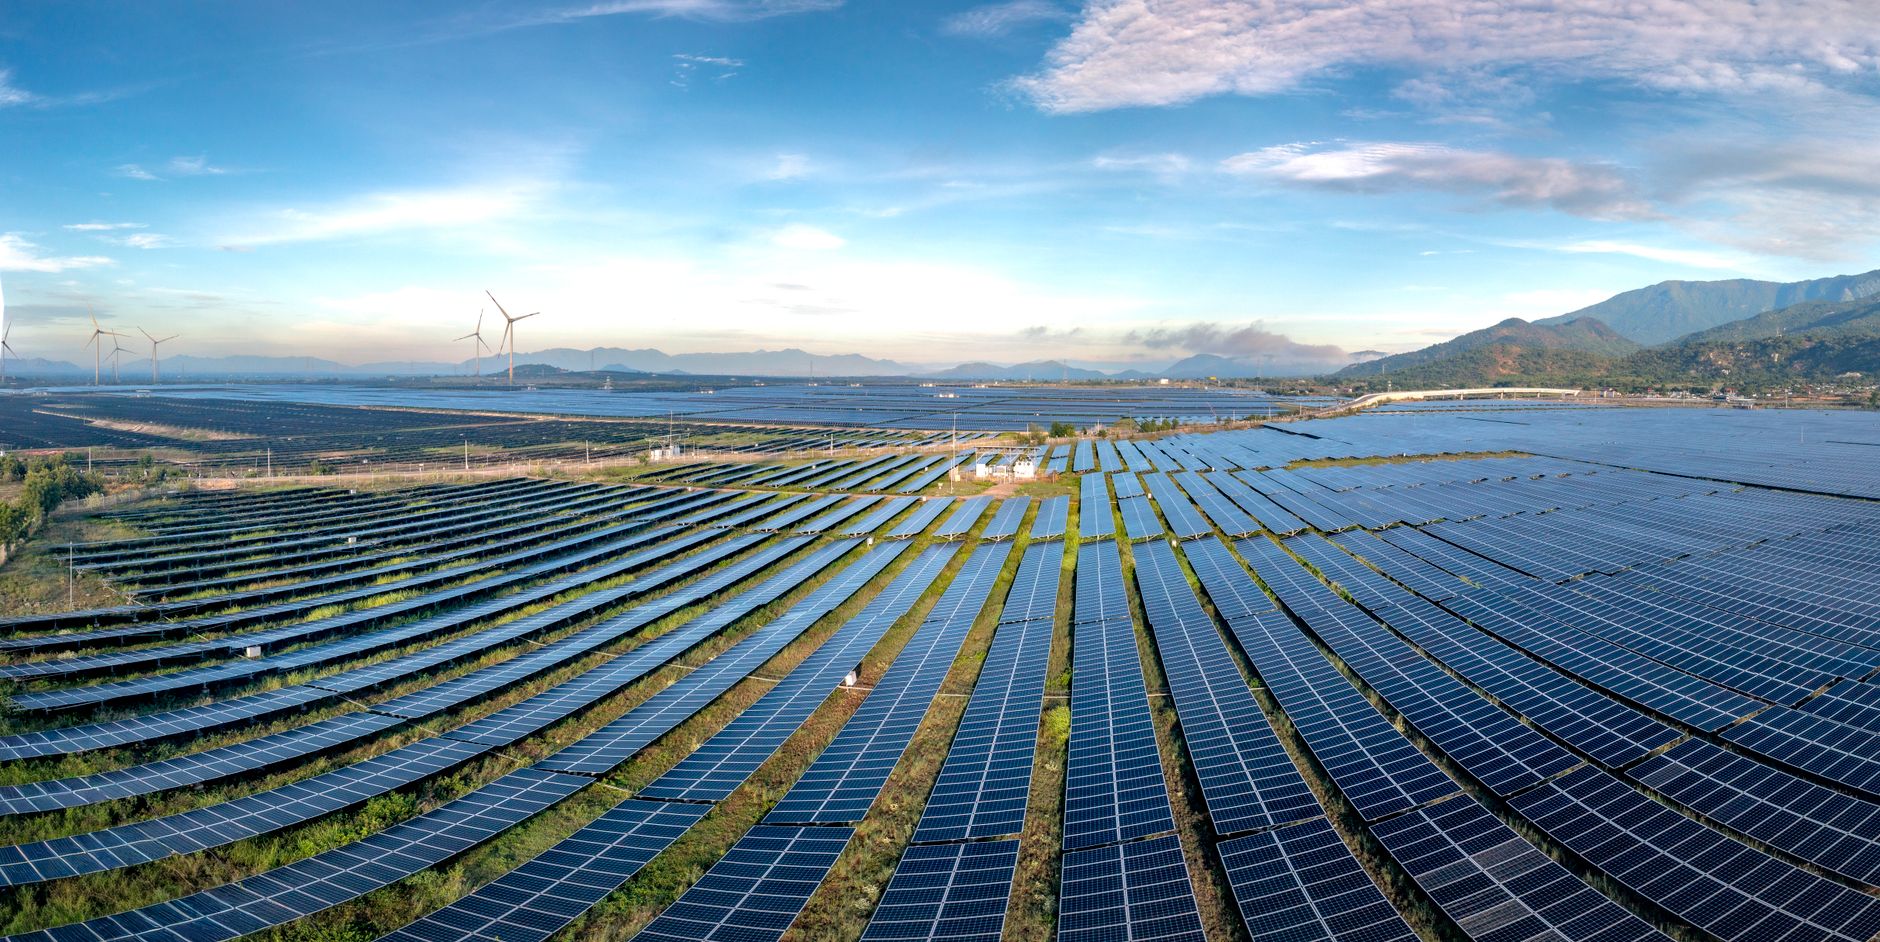
The production economics begin with electricity. Electrolysis splits water into hydrogen and oxygen, and the electricity input usually dominates the levelized cost of green hydrogen. Where renewable electricity is cheap and abundant, production costs fall. Where renewable electricity is scarce or expensive, green hydrogen remains above the cost of hydrogen from natural gas. Geographic differences in renewable resources therefore translate directly into differences in project viability.
The comparison with conventional hydrogen is not symmetrical. Natural gas prices move with global fuel markets, while green hydrogen costs track renewable electricity generation costs. In utility-scale solar markets where generation costs have fallen, the gap has narrowed. In those locations, the remaining spread depends on regional gas prices, carbon prices and electrolyser utilisation.
Utilisation deserves particular attention. An electrolyser connected to a dedicated renewable plant only produces when the sun shines or the wind blows. If the plant is designed to capture the cheapest possible electricity, it may run for limited hours each year. Since electrolyser capital costs are recovered per unit of hydrogen produced, low utilisation pushes up the fixed-cost share of every kilogram. The balance between cheap electricity and high operating hours shapes the plant’s overall economics.
Electrolysis: Engineering Behind the Scale Gap
Alkaline and proton exchange membrane electrolysers dominate commercial deployments today. Alkaline systems cost less to build but ramp more slowly. Proton exchange membrane systems respond faster to variable electricity supply but rely on scarce materials such as iridium and platinum in their catalysts. Solid oxide electrolysers operate at high temperature and offer higher electrical efficiency, though they remain less commercially mature. Each technology sits at a different point between capital cost, flexibility and durability.
Scale is a separate constraint. Electrolyser projects built during the early 2020s were small next to the hydrogen demand of a single ammonia plant or refinery, whose consumption can exceed what a project of that era was designed to produce. The supply chain for electrodes, membranes, power electronics and balance-of-plant equipment has to grow by orders of magnitude before large orders become routine. Until then, project developers face long lead times and limited supplier competition.
Degradation adds another layer. Electrolyser stacks do not last indefinitely, and their lifetime depends on operating patterns, cycling frequency, and water purity. A green hydrogen plant designed around cheap solar cycles more often than one running on steady grid supply, and that cycling imposes wear. Replacement costs over the plant’s life must be included in the levelized cost of hydrogen. Early projects are generating the operating data that allows financiers to price stack degradation more accurately.
Water supply is a quieter constraint. Electrolysis requires purified water. In regions with strong solar resources but scarce fresh water, desalination becomes an additional process step. That adds energy consumption and a water treatment plant to the project. It rarely makes a project unworkable, but it adds complexity in locations where developers assumed land and sunlight were the only requirements.
Transport and Storage: The Quieter Barrier
Hydrogen has high energy content per kilogram but low energy content per cubic metre at atmospheric pressure. That mismatch shapes every decision about moving it from production site to consumer. To move meaningful quantities, hydrogen must be compressed, liquefied, or converted into a chemical carrier such as ammonia.
Each option adds cost and losses. Compression works for pipelines and tube trailers but introduces high-pressure equipment and safety requirements. Liquefaction requires cooling to extremely low temperatures and consumes a meaningful share of the energy contained in the hydrogen. Converting hydrogen to ammonia simplifies shipping, but converting it back at the destination adds another industrial step.
This helps explain why early projects with the strongest commercial case often sit next to the existing user: the facility already has hydrogen piping, storage and handling equipment, and the electrolyser can be added behind the existing fence line. Co-location removes a cost layer that can exceed the cost of the electrolyser itself, which makes proximity a commercial advantage rather than a convenience.
Long-distance trade faces larger obstacles. Liquid hydrogen requires new vessel designs and behaves differently from liquefied natural gas. Ammonia carriers already exist, but using ammonia as a hydrogen carrier raises safety, toxicity and reconversion-cost questions. Pilot projects are testing different approaches, and the industry has not yet settled on a dominant transport pathway.
Policy, Certification and the Additionality Debate
Policy support has become the main near-term demand driver in several regions. Subsidies, tax credits and public procurement programmes in Europe, the United States and parts of Asia have created early revenue floors. The detailed rules matter more than the headline funding amounts, because they define what qualifies as green hydrogen and how claims must be verified.
The central disagreement concerns additionality. If an electrolyser draws electricity from the general grid, it may simply increase demand for fossil generation elsewhere. Strict additionality rules therefore require new renewable generation to be built specifically to supply the electrolyser. Developers argue those rules raise costs and slow deployment. Environmental groups and some regulators counter that without additionality, the greenhouse gas benefit can be overstated.
Certification systems sit on top of this debate. Renewable energy certificates can demonstrate that a quantity of renewable electricity was generated and matched to the electrolyser. Annual matching allows a plant to use grid electricity at night and offset it with certificates from another time. Hourly matching narrows that temporal gap but is harder to implement with current monitoring and certification infrastructure. In both cases, the electricity remains pooled on the grid; the claim is an accounting convention, not a statement about specific electrons or automatic dispatch changes.
Where the First Economic Case Tends to Sit
Existing industrial hydrogen demand offers the clearest early market, judged against three criteria: the buyer already handles hydrogen, the required transport infrastructure is largely in place, and the change sits inside the fence line rather than requiring end users to adopt a new fuel. Ammonia production, refining and methanol synthesis already consume large volumes of hydrogen. Replacing a portion of that demand with green hydrogen does not require customers to install new equipment; the main change happens at the production site, where an electrolyser and a renewable power supply are added.
That co-location reduces risk in ways that matter to lenders. The buyer is known, the offtake arrangement is often internal to the same industrial group, and the transport infrastructure already exists. A green hydrogen project next to an ammonia plant can begin production without waiting for new pipeline networks or for vehicle manufacturers to commit to fuel-cell fleets. Some industrial sites have explored pairing electrolysers with floating solar arrays where land is limited, though this does not remove the need to manage variable input.
The second application with long-term logic is long-duration storage. Power systems with high shares of wind and solar eventually need storage that can shift energy across days or seasons. Batteries handle short-duration balancing well, while reservoir hydropower already provides longer-duration flexibility in many systems. Hydrogen stored in salt caverns or pressure vessels can in principle be converted back to electricity during extended periods of low renewable output. The round trip remains lossy, but the service has few direct substitutes where pumped storage and reservoir hydro are unavailable.
Heavy transport and power generation are often cited as demand sources, but they face stronger competition. Battery electric vehicles serve many short-haul transport segments. Trucks, ships and aircraft require more energy density than current batteries offer, but hydrogen-derived fuels must compete with other low-carbon fuels and with the cost of new refuelling infrastructure. In power generation, direct use of electricity is almost always more efficient than converting it to hydrogen and back again.
The Path to Scale
Scaling green hydrogen depends less on inventing new technology than on assembling the surrounding system: cheap renewable electricity, large electrolyser plants, water supply, compression or conversion infrastructure, certification, and a customer willing to pay the premium. A failure in any one element can delay a project regardless of electrolyser maturity.
Development is proceeding unevenly. Regions with cheap renewable power, existing industrial hydrogen demand and clear subsidy rules support clusters of projects. Regions lacking one or more of those conditions remain largely at the demonstration stage. Current project geography points toward a patchwork of hydrogen hubs around ports, refineries and fertiliser plants, rather than a uniform global market.
Several uncertainties remain open. Electrolyser degradation under real-world cycling is still being measured. Certification rules are still tightening. Transport infrastructure for hydrogen and carriers is mostly unbuilt. Gas prices, carbon prices and renewable electricity costs continue to shift the competitive position of green hydrogen relative to conventional production and direct electrification.
Green hydrogen offers a focused tool for the parts of the industrial system where electrons are difficult to use directly. Whether it expands beyond those applications depends on the cost and transport barriers falling far enough to make it a practical option rather than a strategic one. The current evidence points toward early growth in industrial hubs, followed by a more uncertain expansion into storage and long-distance trade if the first wave of projects performs as designed.
References
- IEA — World Energy Outlook 2025 hydrogen demand, production route and electrolyser deployment data.
- IRENA — Renewable Power Generation Costs 2024 analysis of renewable electricity cost trends and implications for electrolysis economics.
- IRENA — Corporate Sourcing of Renewables material on renewable electricity procurement, certificates and matching frameworks.
- GHG Protocol — Scope 2 Guidance principles for accounting renewable electricity claims and additionality language.