Moving power across a national border once meant completing two separate transactions. A trader bought the energy in one country, then separately secured a physical transmission right on the cross border electricity interconnectors linking the two networks. If either step failed, the trade collapsed, even when the price gap made it economically attractive. That friction pushed Europe toward market coupling, which treats cross-border capacity as a shared resource rather than a separately tradable asset.
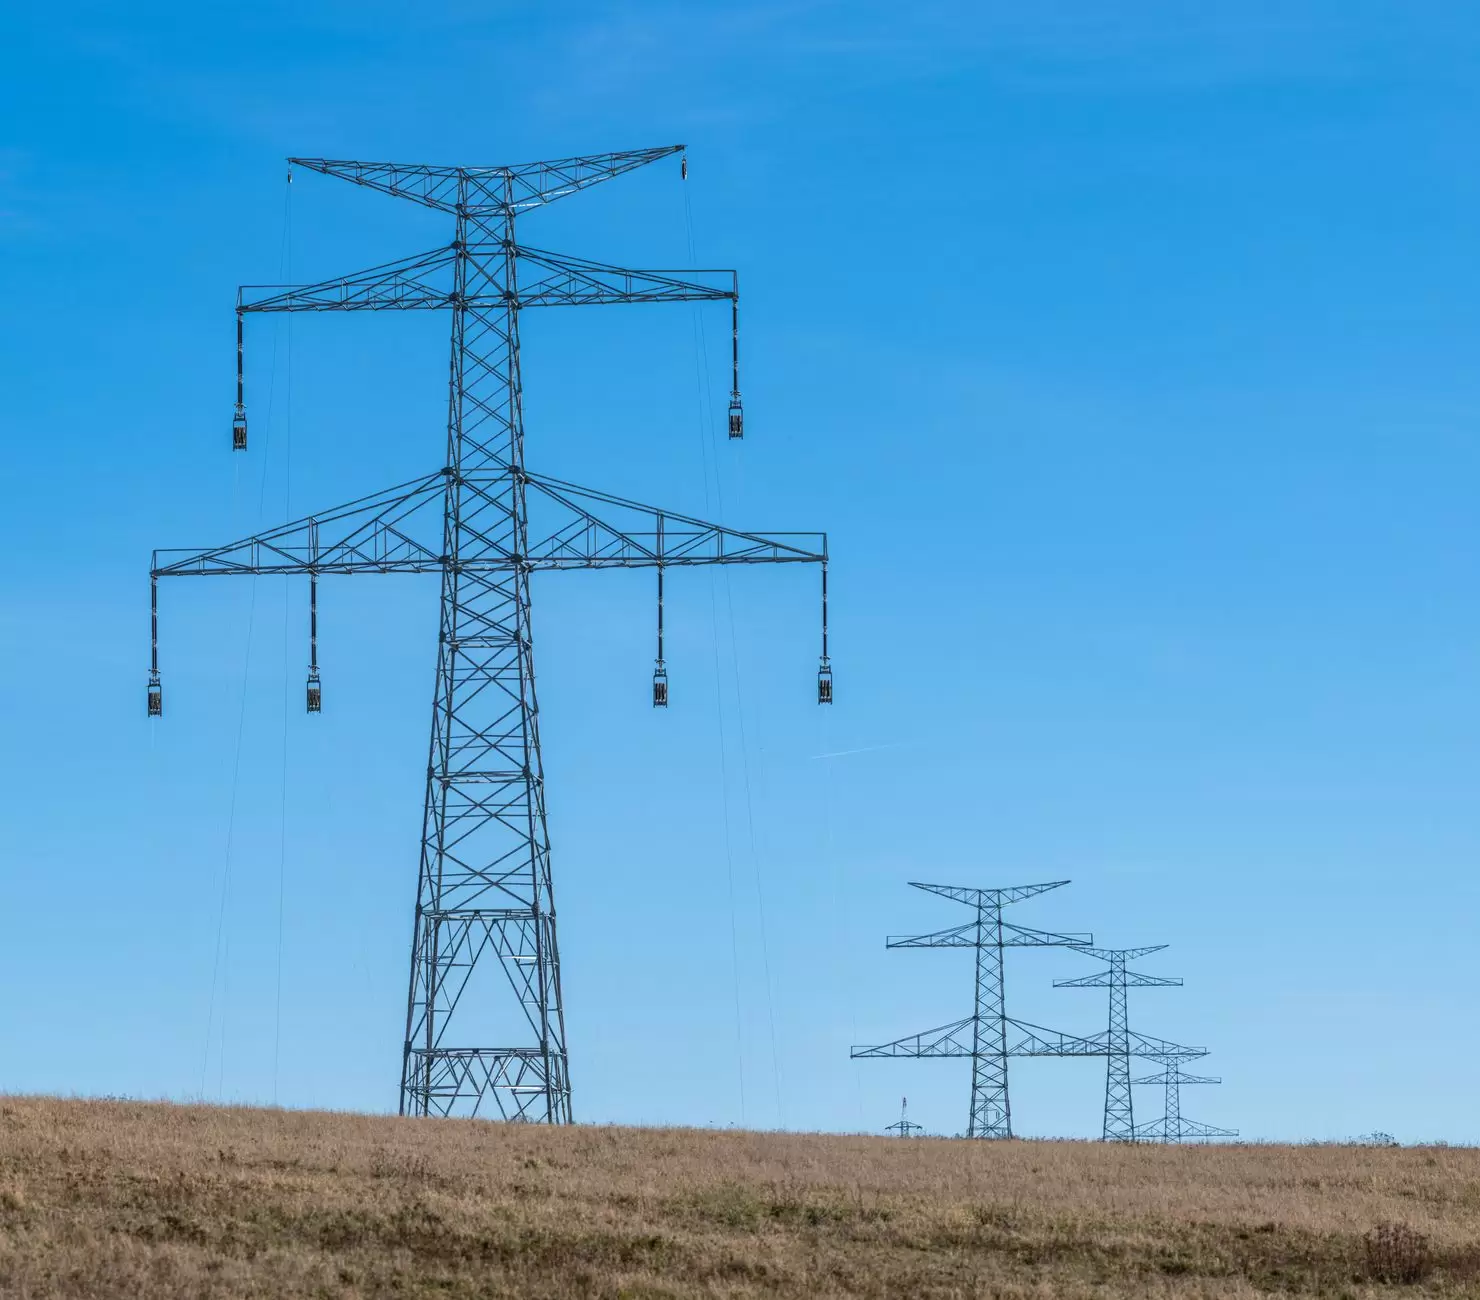
Interconnectors are the high-voltage links that let power move between national networks. They sit inside the wider system described in Transmission Infrastructure: How the High-Voltage Grid Moves Power, connecting markets that would otherwise operate in isolation. In Europe, the rules that govern those links matter almost as much as the cables themselves.
Market coupling replaces the two-step process with a single coordinated market-clearing arrangement. Power exchanges and transmission system operators share one algorithm across multiple countries. The interconnector is not booked separately by traders. Instead, its capacity is allocated by the same optimisation that clears the day-ahead market, using the trades that maximise total value across the region. A trader buys energy in one zone and sells in another, and the algorithm schedules the cross-border flow when the price difference justifies it. The capacity allocation decision moves from a bilateral border auction into a common market process.
Where Market Coupling Came From
Market coupling emerged from two pressures. The European Commission wanted a single internal electricity market, and grid operators faced growing evidence that explicit auctions misallocated scarce interconnection capacity. The Commission’s 2015 guideline on capacity allocation and congestion management later codified the target model, but the operational motivation predates that rule.
Under explicit auctions, transmission rights were sold separately from energy. A trader could hold a profitable French purchase and a German sale but lack the border right, leaving the deal unexecutable. Capacity was also bought at times for reasons unrelated to the day’s actual economics. Traders could hold unused rights while price differences between zones persisted. At other moments, flows moved against the price signal because capacity had already been assigned.
Congestion itself came from the physical limits of the network, not from the way capacity was sold. What explicit allocation could do was worsen the economic consequences: scarce interconnector capacity went underused or was used in the wrong direction, and cross-border trade cost more than the network constraints alone would have implied.
Early coupling pilots in northwestern Europe tested whether a single algorithm could combine energy offers and border capacity in one optimisation. The trilateral arrangement linking France, Belgium and the Netherlands demonstrated the core principle: when transmission capacity is included in the spot market clearing, the need for a separate border right disappears. The flow is allocated implicitly. A trader buys and sells energy in two zones, and the algorithm schedules the interconnector flow when the price difference justifies it.
How Single Day-Ahead Coupling Allocates Shared Capacity
In the day-ahead timeframe, the European target model follows a coordinated sequence. Each transmission system operator first calculates the transmission capacity available across bidding-zone borders for the next day. That figure reflects security margins, anticipated network conditions and forecast uncertainty. It is not simply the thermal rating of the cable. The physical network itself imposes limits that differ from a simple rating.
Each power exchange then collects and anonymises bids and offers from market participants in its zone. A common algorithm solves a market-clearing problem that seeks to maximise total economic welfare across all zones while respecting the capacity limits between them. When the price difference between two zones is large enough and capacity is available, the algorithm schedules flow from the lower-priced zone to the higher-priced one. If the capacity constraint binds, prices separate. If there is spare capacity, prices equalise.
This produces a distinctive feature: interconnector capacity is allocated by the same market-clearing logic that decides which generators run. No separate border auction decides who may use the interconnector. The market selects the set of trades that increases total surplus the most. This does not mean the interconnector has no owner; its physical assets remain under the control of transmission system operators. The allocation decision, however, sits inside the common market process rather than a bilateral border auction.
Capacity Calculation: Why the Cable Rating Is Not the Constraint
A common assumption is that the rated capacity of an interconnector defines the limit on cross-border trade. In practice, the capacity offered to the market is often lower than the physical rating, sometimes considerably lower. Operators keep margins for outages, reserve activation, and uncertainty in renewable generation forecasts. They also must manage the fact that electricity does not follow a simple point-to-point path from seller to buyer.
In the synchronous European network, a transfer scheduled between northern Germany and Austria can loop through Poland, the Czech Republic, the Netherlands or Belgium depending on network conditions. These loop flows mean a border’s available capacity cannot be treated in isolation. A transaction in one part of the grid can consume capacity on a border several countries away. The older available transfer capacity method handled this by publishing a simplified limit for each border. The flow-based market coupling now used in much of Central Western Europe, governed by ENTSO-E’s capacity calculation methodology, instead limits the net position of each bidding zone. That approach better reflects how power physically spreads across the network.
The move to flow-based allocation has consequences. A transaction in one country can affect the capacity available to trades elsewhere, and the algorithm must manage those interactions. The amount of capacity offered can also change hour by hour with wind and solar output, imports and exports, and planned maintenance. That variability reflects the underlying network rather than a failure of the mechanism. The same constraints help explain why tools like Grid-Enhancing Technologies attract interest: they attempt to increase the transfer capacity that can be safely offered in the first place.
Direct-current interconnectors introduce a further layer. Depending on the converter technology, operators can control the direction and speed of power flow in different ways. Some HVDC links can adjust flow rapidly; others operate with fixed or semi-fixed schedules. These technical choices interact with market coupling because they determine whether a given link can participate in intraday and balancing timeframes, or whether it is effectively committed to day-ahead positions. The distinction between line-commutated and voltage-source converters directly affects how flexible the link is inside a coupled market.
What Europe’s Market Coupling Can Teach Other Regions
Market coupling works in Europe because the participating countries share institutions, legal frameworks and operational practices that make a common algorithm possible. Those conditions do not exist everywhere. The model depends on common gate closure times, consistent bidding zone definitions, agreed procedures for handling orders, and trust among transmission system operators. Regions without that coordination cannot simply adopt the algorithm and expect the same result.
Three operational principles travel better than the full European architecture. First, coupling requires a shared price signal across the zones being integrated; without common timing and compatible order types, cross-border optimisation cannot work. Second, capacity calculation and market operation should be separate functions. Grid operators define what is physically safe, while the market decides how that capacity is used. Combining the roles leads either to over-conservative limits or to security risks. Third, transparent capacity data builds participant confidence. When traders can see how much capacity is offered and why it changes day to day, they can distinguish genuine congestion from rule-driven restrictions.
Other models reach similar economic outcomes through different institutional paths. Some North American markets use nodal pricing with centralised dispatch across a single system operator, which internalises many of the same trade-offs without needing a border algorithm. Europe’s contribution is a demonstration that separate national markets can be integrated by market rules alone, without a single system operator. The transferable insight is that the rules for sharing cross-border capacity shape behaviour as much as the physical cables do. Different jurisdictions face their own versions of the coordination problem, whether through border auctions or through backlogged connection processes such as those covered in Interconnection Queue Reform.
Adding new interconnectors remains slow, and market coupling cannot replace physical infrastructure. The efficiency gains from coupling improve the use of existing cables, but they do not remove the need for new capacity when underlying demand grows or generation patterns shift. The build-out of transmission continues to lag behind generation and demand changes in many regions, a mismatch explored in Why Transmission Is Becoming the Biggest Bottleneck in the Energy Transition. Coupling changes how efficiently existing assets are used, not how quickly new ones can be permitted and built.
What to Watch Next
The European target model now extends beyond the day-ahead auction. Intraday coupling lets participants adjust positions closer to real time, and cross-border balancing platforms are gradually reducing the cost of procuring reserves. The direction of travel points toward coordination across all electricity timeframes, rather than only the single day-ahead slot that first demonstrated the concept.
Remaining questions include how to govern bidding zones, how to treat cross-border capacity in capacity remuneration mechanisms, and how to value resilience alongside market efficiency. Europe’s experience shows that coupling is an operational and regulatory project as much as an engineering one. The cables matter, but the rules that decide how they are shared matter at least as much.
References
- European Commission — Commission Regulation (EU) 2015/1222 establishing a guideline on capacity allocation and congestion management: framework for day-ahead and intraday market coupling
- ENTSO-E — Capacity Calculation and Flow-Based Market Coupling Methodology Documentation: explanations of bidding zone constraints, flow-based allocation, and single day-ahead coupling
- IEA — Electricity 2025: context on cross-border interconnector utilisation and the integration of variable renewables in European markets